

Hello, and welcome to Regions & Reasons.
Last week was packed with data, and full of surprises. PCE came in below expectations, payrolls missed, and the two previous months were revised lower. Last but not least, unemployment ticked up. That was enough to lift investors’ mood and take an October Fed hike off the table: by Friday, the odds had fallen to 14%, from 70% at the start of the week.
On the geopolitical front, there were several attempts to unblock the Strait of Hormuz, and the G7 agreed to release up to 100 million barrels from emergency stocks to bring fuel prices down. But we need to stay alert: the US is reportedly sending a third aircraft carrier to the region.
So what changed? Nothing, really. Markets are still in limbo, waiting for more data before they can make a firmer call. In the meantime, yields keep grinding higher, and analysts are getting more nervous by the day.
The week in five lines:
• Macro: geopolitics and US Treasury yields are what matter most this week.
• Indices: the S&P 500, my benchmark, sits about 1% below its record close.
• Rates: yields keep climbing and keep analysts on edge; the 10-year touched 5.34% on Thursday, its highest since 2002.
• Dollar: higher yields and geopolitical stress should keep the dollar firm.
• Oil and gold: both can keep sliding as long as the efforts towards a temporary deal on Hormuz continue.
• What could change everything: an escalation in the Gulf, or yields climbing out of control.
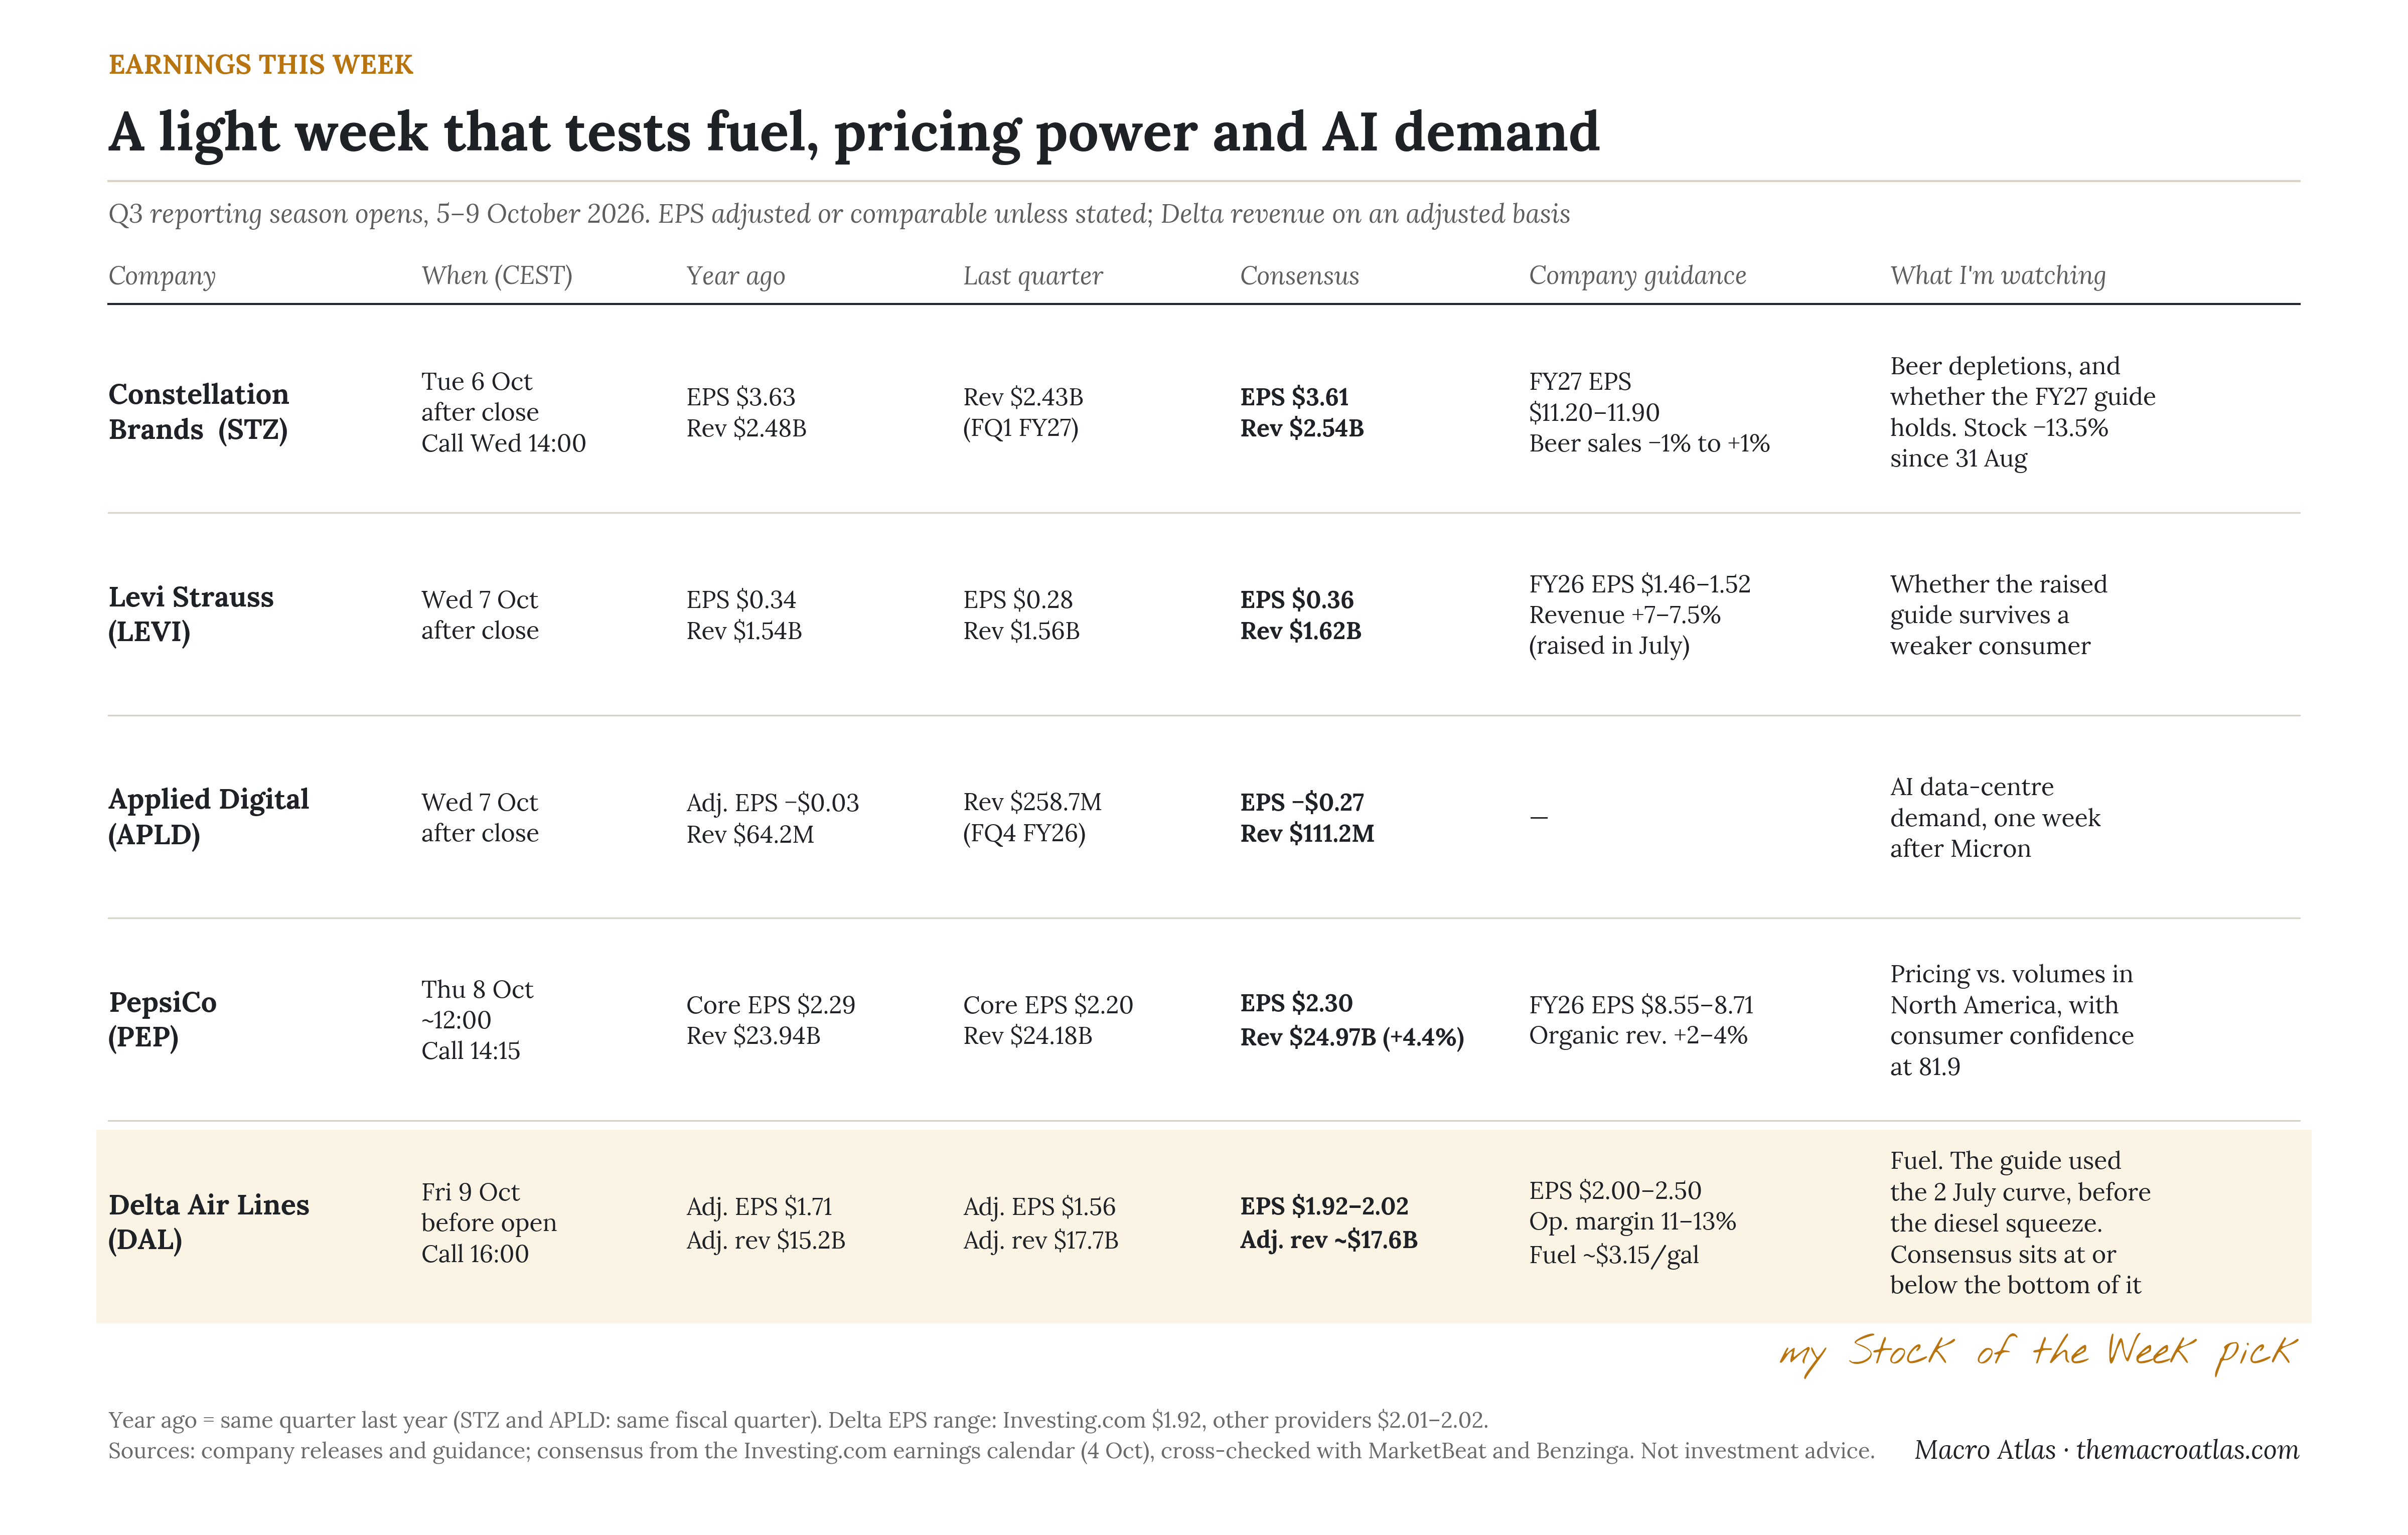
The full map, with the big picture, rates, the week ahead and every region I'm watching, is in the PDF below.
